
An HMRC winding up petition is the most serious step HMRC can take against your company — but it is not, yet, a winding up order. Nothing is decided until the hearing, and petitions are settled, stopped and dismissed every week.
What makes the next few days critical is one date. Roughly seven business days after the petition is served, HMRC can advertise it in the Gazette — and that advertisement triggers frozen bank accounts and the spiral that follows. Act before it, and you still have real options. This guide covers the timeline, every way to stop a petition, what it costs, and the risks for directors.
This guide reflects HMRC guidance as reviewed on 2 November 2026.
An HMRC winding up petition is a court application by HMRC asking for a company to be placed in compulsory liquidation because it cannot pay its tax debts. HMRC petitions under section 122(1)(f) of the Insolvency Act 1986. The petition is advertised in the Gazette about seven days after service.
Important: this article is general information only, not legal advice. It explains the process in England and Wales; it cannot cover your company’s position. If a petition has been served on your company, take advice from a licensed insolvency practitioner or solicitor immediately: the deadlines run in days.
What an HMRC winding up petition is
An HMRC winding up petition is a formal application to the court, presented by HMRC as a creditor, asking for your company to be wound up — placed in compulsory liquidation — because it is unable to pay its debts. If the court makes a winding up order, the Official Receiver takes control and the company’s assets are sold to pay creditors.
A petition is not an order. Between the two sits a court hearing, usually weeks away, and the outcome is not fixed. HMRC presents more winding up petitions than any other creditor, largely because tax arrears build up silently — and tax changes keep squeezing cash flow, as our round-up of the Autumn Budget 2025 small business changes shows.
HMRC does not have to serve a statutory demand before petitioning, although demands, warning letters and Time to Pay offers normally come first.
The tax debts that trigger petitions
Petitions against small companies usually rest on VAT, PAYE and employer National Insurance, Corporation Tax, or Construction Industry Scheme (CIS) deductions — often a mix. See our guide to employer National Insurance contributions for the PAYE side.
Two traps recur. First, VAT assessed under a Best Judgment Assessment because returns were never filed — HMRC’s estimate, often far higher than the real liability. Second, a defaulted Time to Pay arrangement — once an agreed plan fails, HMRC rarely offers another.
Since 1 December 2020 (Finance Act 2020), HMRC has ranked as a secondary preferential creditor for VAT, PAYE, employee National Insurance and CIS deductions — taxes collected from others. Corporation Tax and employer National Insurance are not covered.
The law behind it — and why “section 194” is the wrong section
There is no winding up power in section 194 of the Insolvency Act 1986, and any reference to it — in a letter or online — is wrong. Section 194 is headed “Resolutions passed at adjourned meetings” — meeting procedure, not closing companies down.
The provisions HMRC actually relies on are these:
- Section 122(1)(f) — the ground for the petition: the court may wind up a company if “the company is unable to pay its debts”.
- Section 123 — defines what “unable to pay its debts” means, through the tests explained below.
- Section 124 — who may present a petition — including any creditor, which is HMRC’s capacity here.
- Section 127 — any disposition of company property made after the petition is presented is void if a winding up order follows, unless the court orders otherwise — the reason bank accounts freeze, and validation orders exist.
Each is published in full on legislation.gov.uk.
The two insolvency tests in section 123
HMRC must show your company is unable to pay its debts, and section 123 gives it several routes. The simplest is section 123(1)(a): a creditor owed more than £750 serves a statutory demand at the company’s registered office, and the company neglects for three weeks — 21 days — to pay, secure or compound the debt. The deemed insolvency follows automatically.
Beyond that are two court tests. The cash-flow test (section 123(1)(e)) asks whether the company cannot pay its debts as they fall due. The balance-sheet test (section 123(2)) asks whether its assets are worth less than its liabilities, including contingent and future ones. HMRC only needs one route to succeed.
The timeline — from first demand to winding up order
The key deadline is already in your hands: the hearing date is printed on the petition. Hearings are commonly listed six to ten weeks after presentation — listing speeds differ between courts — but the advertisement deadline arrives far sooner.
| Stage | When | What happens |
|---|---|---|
| Tax payment missed | Weeks to months before | Reminders, demands, warnings; possible Time to Pay offer |
| Statutory demand (if used) | 21 days to pay | Unpaid after 21 days, the company is deemed unable to pay its debts (section 123(1)(a)) |
| Petition presented and served | Day 0 | Petition filed at court and served at your registered office |
| Advertisement window opens | 7 business days after service | Earliest HMRC may advertise (rule 7.10, Insolvency Rules 2016) |
| Gazette advertisement | At least 7 business days after service, and at least 7 business days before the hearing | The petition becomes public; banks normally freeze accounts within 24–48 hours |
| Opposition deadline | 5 business days before the hearing | Last day to file a witness statement opposing the petition (rule 7.16) |
| Court hearing | Typically 6–10 weeks after presentation | Winding up order, dismissal, or adjournment |
| Winding up order | Hearing day | Official Receiver takes control; liquidation begins |
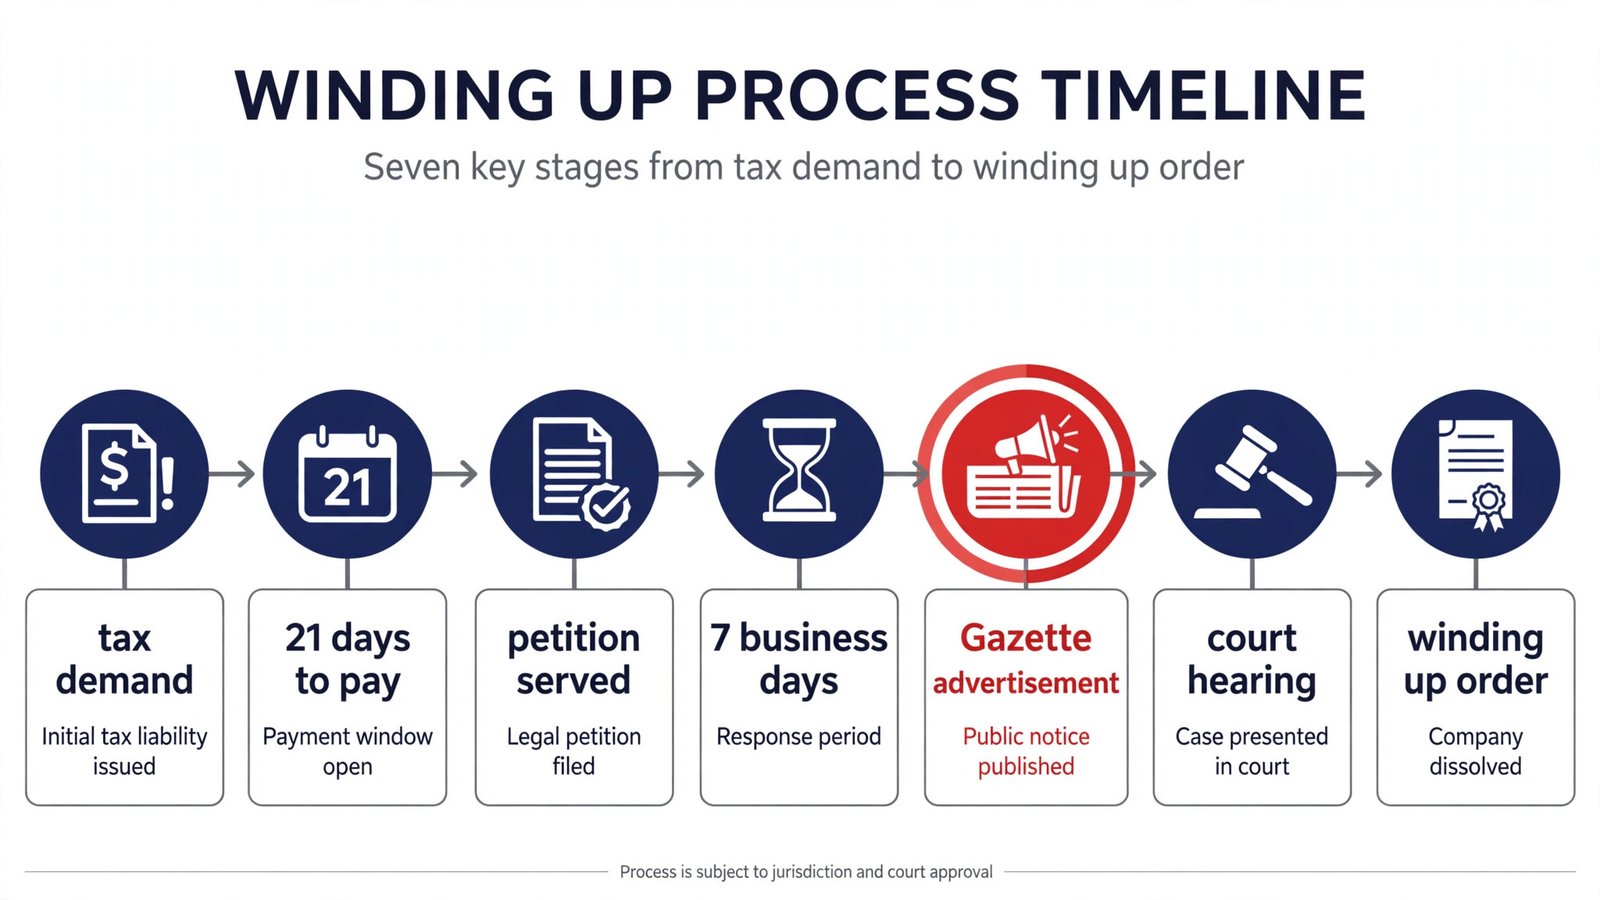
Before any of this comes HMRC’s escalation ladder: missed-payment letters, debt management contact and a warning that a petition may follow. None of those stages is the petition itself — but each means it is closer.
Warning: the petition is served at your registered office, whether or not anyone collects post there. If your Companies House address is out of date, a petition can be under way before you know it. Keep the address current, and check the Gazette if you are in arrears.
What happens when the petition is advertised
The advertisement is the cliff edge, not the hearing. Once notice of the petition appears in the Gazette, the systems that watch for it react immediately.
Banks monitor Gazette notices and routinely freeze company accounts. The reason is section 127: if an order is later made, the winding up is treated as having begun when the petition was presented (section 129), so account payments after that point are void unless validated. Freezing protects the bank. A freeze usually follows within a day or two of the advertisement — occasionally earlier, if the bank learns of the petition another way, for example as a lender.
Suppliers move you to cash on delivery, customers pause orders, and credit insurers withdraw cover. Other creditors can see the petition too: any of them can give notice to support it, and under rule 7.17 of the Insolvency Rules 2016 the court can substitute another creditor as petitioner. That is why paying HMRC alone does not always end the matter.
You can still trade until an order is made — but every payment carries section 127 risk without a validation order. Act before the advertisement.
Your options to stop an HMRC winding up petition
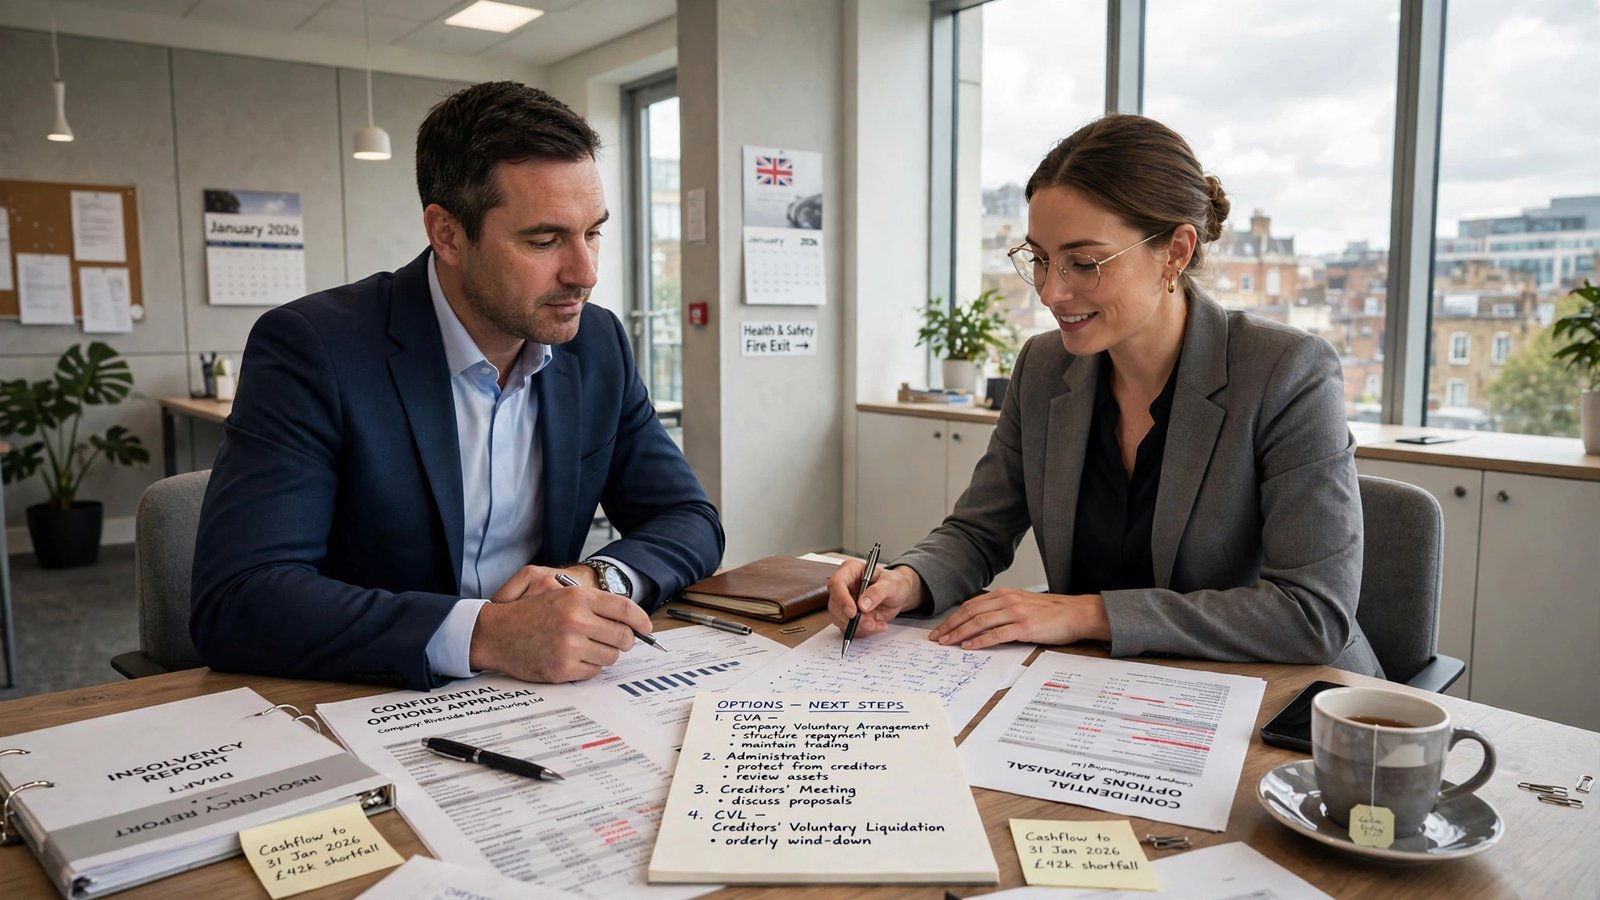
A petition can be stopped at any point before the hearing — sometimes even after one. Which route works depends on three questions: is the debt right, can it be paid, and is the business viable? The eight realistic options, compared:
| Option | What it involves | Best when | Watch out for |
|---|---|---|---|
| Pay in full and get it dismissed | Pay the debt plus HMRC’s costs and obtain a court dismissal | You can raise the money quickly | Payment alone is not enough — petition stays live until dismissed |
| Dispute the debt | Show a genuine, substantial dispute, or a miscalculation | HMRC’s figures rest on estimates or errors | The dispute must be real and evidenced, not a delaying tactic |
| Time to Pay | Negotiate instalments with HMRC after the petition | The debt is right but cash flow is temporarily short | Much harder post-petition; needs lump sum and forecasts |
| Injunction | Urgent court order restraining advertisement | Debt genuinely disputed; advertisement window still open | Urgent and costly; refused if the case is weak |
| Validation order | Court permission under section 127 for specified payments | Accounts frozen but the business can trade profitably | Evidence-heavy; each payment must be justified |
| Adjournment | Ask the court to postpone the hearing | A payment, deal or rescue is genuinely close | Speculative delay fails; bring concrete progress |
| CVA | Binding repayment deal over 3–5 years | The business is viable but the debt load is not | Needs 75% by value of voting creditors, including HMRC |
| Administration or CVL | Formal process halting or replacing the petition | Rescue, or orderly closure if the business cannot be saved | Out-of-court administration appointment is blocked once a petition exists |
Pay the debt in full — and get the petition dismissed
Paying clears the ground for dismissal, but does not dismiss the petition by itself. The petition stays on the court record until the court formally dismisses it, and you will normally have to cover HMRC’s petition costs as well as the debt. Pay early if you can — ideally before the advertisement — and have your solicitor confirm the dismissal is sealed.
Dispute the debt
A winding up petition is not a debt-collection tool for debts genuinely in dispute. In Stonegate Securities Ltd v Gregory [1980] Ch 576, the Court of Appeal confirmed that where a company disputes a debt in good faith and on substantial grounds, the petition will be dismissed or its presentation restrained. With HMRC, the commonest real dispute is the Best Judgment Assessment: file the missing returns, and the estimate is replaced by the true figure, which may be far lower. Pay any part you accept is due. Defective service can also be challenged: in DG Resources Ltd v HMRC [2026] EWHC 201 (Ch), a petition was struck out for service that broke the Insolvency Rules’ service code.
Ask HMRC for Time to Pay
Time to Pay is still possible after a petition, but much harder: the file sits with HMRC’s enforcement side, not the helpline. Expect to need all returns filed, credible forecasts and an upfront lump sum. Practitioners report that a meaningful first payment is what gets a proposal taken seriously; any figure quoted for it is negotiation practice, not a rule.
Stop the advertisement — injunction
If the debt is genuinely disputed, you can apply urgently for an injunction restraining HMRC from advertising the petition. Its value lies in keeping the petition out of the Gazette and your bank account open. Courts grant injunctions where the dispute is real or a rescue genuinely advanced, not as a breathing-space device.
Apply for a validation order
A validation order is the court’s permission, under section 127, for specified payments despite the petition — wages, key suppliers, rent. The test, from Re Gray’s Inn Construction Co Ltd [1980] 1 WLR 711, is that the payments must benefit creditors generally. One firm reports a recent case costing around £20,000 in fees — a warning about potential cost, not a going rate.
Ask the court for an adjournment
Judges adjourn petition hearings where there is concrete progress to point to: an agreed proposal, refinancing in writing, or a CVA or administration genuinely in preparation. They do not adjourn for hope. Arrive with documents, dates and evidence of what will be different by then.
Propose a CVA
A Company Voluntary Arrangement, under Part 1 of the Insolvency Act 1986, binds all unsecured creditors to a repayment deal over three to five years. Approval needs at least 75% by value of the creditors who vote (rule 15.34 of the Insolvency Rules 2016), and fails if more than half by value of unconnected creditors vote against. HMRC’s preferential status gives its vote real weight. Once approved, the petition is normally dismissed.
Administration, or a CVL if the business cannot be saved
Administration places a moratorium around the company that halts the petition. One catch matters: under paragraph 25 of Schedule B1 to the Insolvency Act 1986, the company and its directors cannot appoint an administrator out of court while a petition is pending — that needs a court application instead. If the business cannot be saved, a creditors’ voluntary liquidation (CVL) lets directors choose the timing and liquidator — far better on conduct than a compulsory liquidation.
Worked example — what it costs to make a petition go away
Here is the arithmetic, with every figure labelled — your numbers will differ. Say a small company is petitioned over £48,000 of VAT and PAYE arrears. That debt figure is illustrative. To clear the petition by payment, the company must find:
- The debt itself: £48,000 (illustrative)
- HMRC’s petition costs: GOV.UK publishes the court fee at £352 and the petition deposit at £2,600 — £2,952 before legal costs. All-in, with solicitors, petitioner costs are commonly estimated at £3,500–£4,000, and the company will usually have to cover them to get the petition dismissed
- Its own advice: a solicitor or licensed insolvency practitioner to check figures, negotiate and secure dismissal
On those figures, the planning total is roughly £52,000–£53,000 — the petition process has added around £4,000–£5,000 of dead cost on top of the tax itself. A frozen account and a validation order push costs higher still.
The same £48,000 settled at the demand stage costs £48,000. Every stage after that adds fees that buy the company nothing.
The risks for directors if a winding up order is made
Directors are not automatically liable for a company’s tax debts — limited liability still means something. But a winding up order triggers an investigation into how the company was run — the Official Receiver, then any liquidator, typically reviews the three years before the order — and several specific risks follow. The main exposures, at summary level:
- Disqualification. Under section 6 of the Company Directors Disqualification Act 1986, a director whose conduct makes them unfit can be disqualified for between 2 and 15 years.
- Wrongful trading (section 214). If directors kept trading when they knew, or ought to have concluded, there was no reasonable prospect of avoiding insolvent liquidation, without taking every step to minimise losses to creditors, the court can order personal contributions.
- Misfeasance (section 212). Misuse of company money or breach of duty can be pursued and repaid personally.
- Earlier transactions unwound. Preferences (section 239) given in the six months before insolvency — or two years for connected persons — and transactions at an undervalue (section 238) within two years can be reversed under section 240.
- Overdrawn director’s loan account. Any balance you owe the company becomes repayable to the liquidator on demand — see our guide to the overdrawn director’s loan account.
- Personal guarantees. Guarantees you signed — bank, landlord, supplier — are called in against you personally.
- Personal and joint liability notices. HMRC can transfer specific tax debts to individuals in defined cases: personal liability notices for PAYE and National Insurance failures involving fraud or neglect, and joint and several liability notices (Finance Act 2020) in avoidance and repeat-insolvency cases.
Employees are dismissed automatically when a winding up order is made. They can claim arrears of pay, holiday pay, notice pay and redundancy from the National Insurance Fund through the Redundancy Payments Service, subject to statutory caps.
Your first 24 hours — a checklist
The first day is about not making things worse, and getting the right people in the room. In order:
- Read the petition. Note the petitioner, the amount, the court — and the hearing date printed on it.
- Check the Gazette. Search the Gazette for your company — whether it has been advertised decides how urgent everything else is.
- Stop non-essential payments. Post-petition payments risk being void under section 127. Do not move money beyond reach — that creates the preference and undervalue problems described above.
- Call a licensed insolvency practitioner or insolvency solicitor today. Regulated, time-critical work; the first call is usually free.
- Gather the numbers. Latest accounts, management figures, the tax position tax by tax, and a realistic cash-flow forecast.
- Check HMRC’s figures. Compare the petition debt against your filed returns — estimates and errors happen.
- Be careful who you tell, and how. Do not mislead your bank or suppliers, but take advice on what to say first.
Frequently asked questions
Can HMRC issue a winding up petition without a statutory demand?
Yes. A statutory demand is one way of proving a company cannot pay its debts — not a legal prerequisite. HMRC can rely on unpaid, overdue tax and the cash-flow test in section 123(1)(e) instead. Their absence does not invalidate a petition.
How long do I have before the petition is advertised in the Gazette?
About seven business days from service. Under rule 7.10 of the Insolvency Rules 2016, the advertisement must appear not less than seven business days after service, and not less than seven business days before the hearing.
Can I still pay staff wages after a petition is served?
The honest answer is: not safely, without help. Payments made after the petition was presented are void if a winding up order follows, unless the court validates them (sections 127 and 129). Once the account is frozen, wages normally need a validation order. Take advice immediately — payroll deadlines do not wait.
I have paid HMRC in full — is the petition over?
Not yet. The petition stays live on the court record until the court formally dismisses it, and creditors who supported it can ask to be substituted and keep it going (rule 7.17). Make sure the dismissal is ordered and sealed, with HMRC’s costs covered.
Can a petition be stopped after it has been advertised?
Yes, but harder and more expensive. All the options above remain available — the damage from publicity and frozen accounts is just harder to undo. Even after an order, the court can stay the winding up under section 147, but that is exceptional. Treat the hearing as the real deadline.
Will I personally have to pay the company’s tax debts?
Usually, no — limited liability is the default, and the company’s debts are the company’s. The exceptions are specific: guarantees you signed, an overdrawn director’s loan account, personal and joint liability notices, and court orders for wrongful trading or misfeasance. Our guide to a director’s tax responsibilities covers the wider picture.
What happens to employees if a winding up order is made?
Their employment ends automatically on the order. Staff can claim arrears of pay, holiday pay, notice pay and statutory redundancy from the National Insurance Fund through the Redundancy Payments Service, subject to statutory caps. The liquidator or Official Receiver will explain how to claim.
Conclusion
An HMRC winding up petition is beatable at every stage before the hearing — but every option decays with time. Payment works best before the advertisement. A dispute works best with evidence assembled early. A rescue works best while the bank account still functions. The advertisement, about seven business days after service, is the point of no easy return, so the only genuinely bad move is to leave the envelope unopened.
Read the petition, find the hearing date, check the Gazette, and get licensed advice today. It costs nothing and keeps every door open.
Disclaimer: This article is general information about the process in England and Wales, checked against GOV.UK and the Insolvency Act 1986 on 2 November 2026. It is not legal or insolvency advice. A winding up petition is urgent and case-specific — speak to a licensed insolvency practitioner or a solicitor straight away.